When Growth Becomes a Liability: Diagnosing the Profitability Erosion Hidden Inside Your Revenue Numbers
The Applause That Should Be a Warning Sign
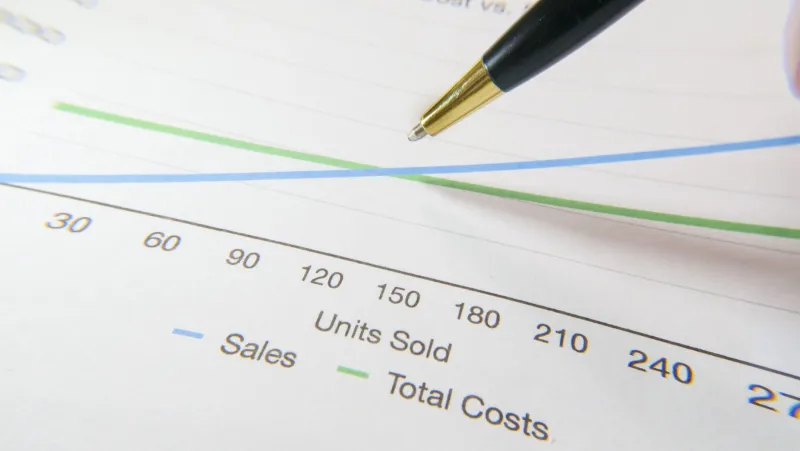
There is a particular kind of boardroom moment that feels like success but functions like a slow leak. Revenue is up — meaningfully up. The sales team is celebrating. The press release is drafted. And yet, somewhere in the finance department, a quieter conversation is beginning about why margins are compressing even as the top line climbs.
This is the margin paradox: the condition in which a B2B company grows its way into a less profitable business. It is more common than most executives care to admit, and it is almost always the product of decisions that looked entirely rational at the time they were made.
Understanding why this happens — and how to detect it before it becomes structural — is one of the most consequential analytical challenges facing growth-oriented B2B firms in the current environment.
How the Trap Is Built, One Decision at a Time
No leadership team sets out to erode its own unit economics. The margin paradox is rarely the result of a single catastrophic choice. It accumulates through a series of individually defensible decisions that, in combination, fundamentally alter the cost structure of serving each customer.
Discounting as a growth accelerant. When pipeline pressure intensifies, discounting becomes the default lever. Sales teams learn quickly that a 15 percent price reduction can close a hesitant prospect in days rather than months. The deal gets booked, the quota gets met, and the pattern repeats. Over twelve to eighteen months, the average contract value drifts downward even as deal volume increases. Revenue grows; revenue quality does not.
Channel expansion without margin modeling. Adding a reseller network, launching a marketplace presence, or building an affiliate program can dramatically expand reach. What these moves often fail to account for is the layered cost structure they introduce — channel fees, co-marketing obligations, implementation support for partner-sourced customers who arrive with less context and higher service demands. The new revenue is real. So is the margin dilution.
Product proliferation in response to market pressure. Competitive dynamics and customer requests push many B2B firms toward feature expansion and adjacent product lines. Each addition carries development, maintenance, and support costs that rarely scale proportionally with the incremental revenue they generate. The result is a product portfolio that is broader, more expensive to sustain, and less defensible on price.
The Metric That Reveals What Revenue Conceals
The diagnostic starting point for any firm concerned about the margin paradox is a rigorous calculation of contribution margin by customer cohort — not in aggregate, but segmented by acquisition channel, contract vintage, deal size, and product configuration.
Most B2B finance teams track gross margin at the company level. Far fewer track what it actually costs to acquire, onboard, serve, and retain a specific type of customer. When that analysis is conducted with discipline, the results are frequently illuminating in uncomfortable ways.
A technology services firm that engaged in this exercise discovered that its fastest-growing customer segment — mid-market accounts acquired through a newly launched partner channel — generated 34 percent lower contribution margins than direct-sourced enterprise accounts, despite carrying similar contract values on paper. The gap was explained almost entirely by elevated onboarding costs, higher support ticket volumes, and accelerated churn rates that triggered customer success interventions the firm had not budgeted for.
The revenue from that channel looked healthy. The economics did not.
A Framework for Realignment
Addressing the margin paradox requires more than cost-cutting. It demands a structural reassessment of which growth activities are worth pursuing at their true, fully loaded cost.
Step one: Establish a unit economics baseline. Calculate customer acquisition cost, average contract value, gross margin per customer, and customer lifetime value across every meaningful segment. If your data infrastructure does not currently support this level of segmentation, building that capability is the prerequisite for everything that follows.
Step two: Rank your growth channels by margin, not volume. A channel that delivers twice the deal volume at half the margin is not necessarily an asset. Evaluate each acquisition pathway against its fully loaded contribution to profitability, including post-sale service costs.
Step three: Establish discount governance with margin floors. Sales discounting should not be a unilateral field decision. Implementing approval thresholds tied to minimum contribution margin targets — rather than simply to deal size — changes the incentive structure in meaningful ways. Sales leaders begin optimizing for deal quality alongside deal volume.
Step four: Audit the product portfolio against revenue contribution. Features and product lines that consume disproportionate engineering and support resources relative to their revenue contribution are margin liabilities. Rationalization is difficult politically but necessary financially.
Growth That Holds Its Value
The goal is not slower growth. It is growth that remains profitable as it scales — growth that improves the business's financial position rather than complicating it. For B2B firms operating in competitive markets, the distinction between revenue growth and value creation is not academic. It is the difference between building an asset and building a problem that becomes harder to solve with each passing quarter.
The margin paradox is diagnosable. It is correctable. But it requires leaders who are willing to look past the top line and ask a harder question: at what cost is this growth being purchased?